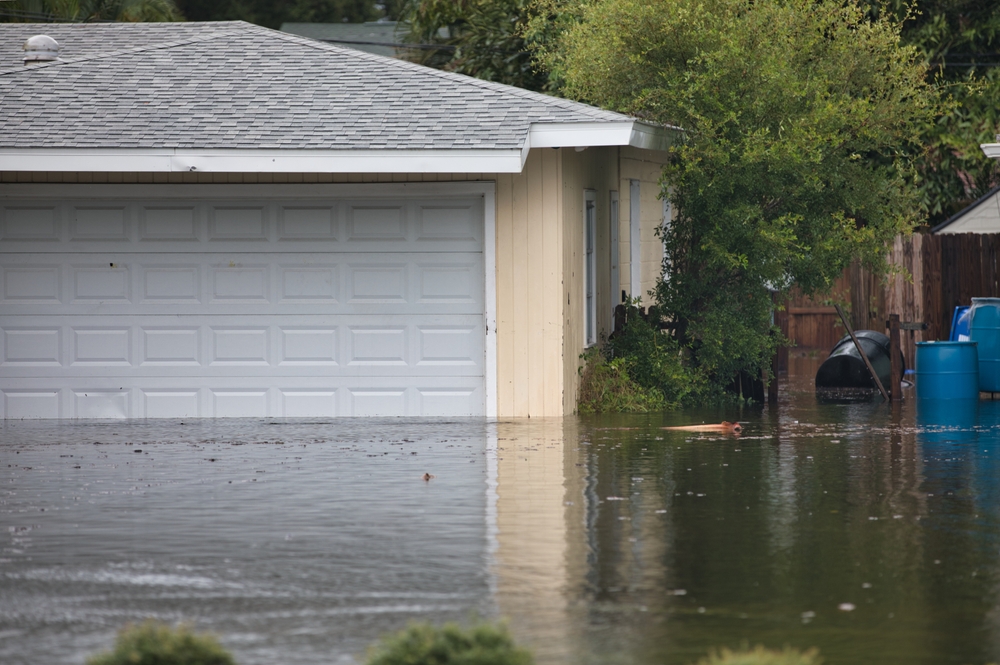


Flood insurance is a separate policy with its own rules, and it deserves serious attention, whether you live near the coast. First and foremost, standard homeowner’s insurance does not cover flooding. Flood damage is specifically excluded, regardless of how the water entered your home or how severe the event was. To be covered for flooding, you need a separate flood insurance policy, either through the National Flood Insurance Program (NFIP) administered by FEMA, or through a private flood insurance carrier.
A flood is defined as a general and temporary condition of partial or complete inundation of normally dry land from overflow of inland or tidal waters, rapid accumulation of surface water, or mudflow. In simpler terms, if water rises from the ground up and enters your home, it is likely a flood event.
Common flood scenarios covered under a flood policy involve the storm surge from a hurricane or tropical storm pushing water inland. A policy also covers rivers or streams that overflow and affect nearby properties. Heavy rainfall that overwhelms storm drains and causes street or yard flooding and enters the home is also covered under a flood policy, as well as tidal flooding in low-lying coastal areas.
By contrast, if rain enters your home through a damaged roof or a broken window during a storm, it is considered wind-driven rain and is typically under your homeowner’s policy, not flood insurance.
NFIP flood policies and most private flood policies provide two types of coverage that are purchased separately. Building coverage protects the physical structure of your home, including the foundation, electrical and plumbing systems, HVAC equipment, water heaters, built-in appliances, flooring, and permanent fixtures. Contents coverage safeguards your personal belongings, such as furniture, clothing, electronics, and portable appliances.
It is important to know that contents coverage is not automatic. You must specifically select it, and many homeowners who purchase only building coverage discover too late that their personal property is not included.
Even with a flood policy, certain losses are excluded. Unlike homeowner’s coverage,NFIP flood policies do not include additional living expense coverage if you are displaced from your home. Cars and other vehicles are not covered under a flood policy and falls under your auto policy’s comprehensive coverage. Also, outside property, including decks, patios, fences, landscaping, and swimming pools, are generally excluded, along with currency, precious metals, and valuable papers, which require separate coverage. NFIP policies also have significant limitations on what is covered in below-grade spaces, so most basement contents are excluded.
Federal law requires flood insurance for federally backed mortgages on properties in high-risk flood zones, designated as Special Flood Hazard Areas (SFHAs) on FEMA’s flood maps. Therefore, Flood Insurance is worth considering even if you are not required by the government or your mortgage company to carry it. FEMA estimates that more than 20% of flood insurance claims come from properties outside high-risk flood zones. Flood maps are also updated periodically, and a property that was not in a flood zone when it was purchased may be designated differently today.
The National Flood Insurance Program has historically been the primary source of flood coverage, but the private flood market has grown significantly in recent years. Private policies offer advantages that NFIP policies do not, including higher coverage limits for both building and contents. If you are displaced by the flood, a private flood policy may cover additional living expenses. You’ll also find broader coverage for items excluded under the NFIP and shorter waiting periods before coverage takes effect. It’s important to note that the NFIP carries a standard 30-day waiting period before a new policy takes effect, with limited exceptions. This means flood insurance cannot be purchased in anticipation of a named storm.
NFIP premiums are based on factors including your property’s flood zone designation, the elevation of the lowest floor, the age and construction of the home, and the coverage amounts selected. Private flood insurance premiums are set by individual carriers and can vary widely. In some cases, private coverage is less expensive than NFIP for lower-risk properties.
Flood is the most common and most costly natural disaster in the United States, and it is the one type of coverage that homeowners discover they are missing too late. If you have not reviewed your flood exposure recently, or if you have never had a flood policy and are unsure whether you need one, it is worth having that conversation with your insurance agent before the next storm.
