

Because many local agents represent companies that specialize in coverage on or near the coast, we’re better equipped to advise you on which policy may be best for you. To start, many homeowners assume their deductible applies to all storm damage, including damage from hurricanes. Like most assumptions, this can be costly. Hurricane deductibles are a distinct feature of many coastal policies, but they work differently from the deductible on a typical claim.
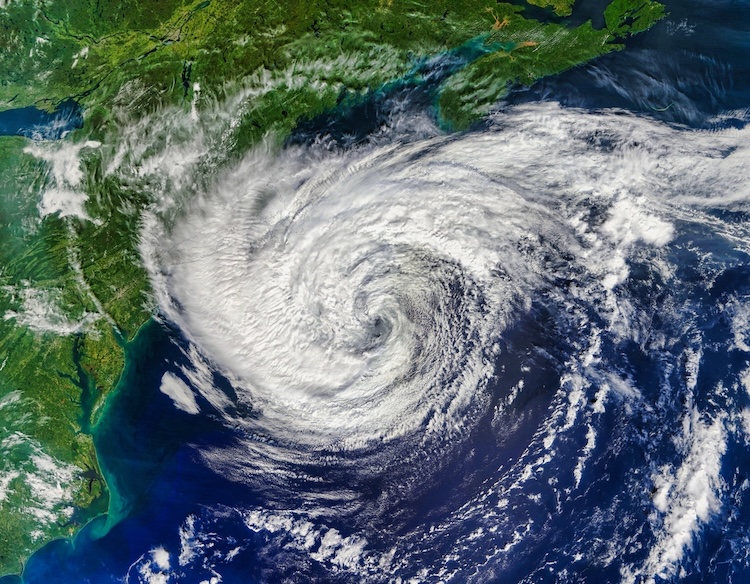
Hurricane and windstorm deductibles often are confused, and with good reason, since they sound very similar. A windstorm deductible applies to wind damage broadly, regardless of the cause of the wind event, while a hurricane deductible kicks in only when damage is caused by a storm officially designated a hurricane (Category 1 or higher) by the National Hurricane Center.
Your policy outlines other triggering events for these deductibles.One Rhode Island insurance carrier defines a hurricane as a tropical cyclone with sustained surface winds of 64 knots (74 mph) or higher. If a storm makes landfall as a hurricane within a specified geographic region and a hurricane watch or warning is issued for your county or region, your deductible likely would go into effect. The specific trigger language varies by carrier and policy, so it is essential to read your declarations page and policy carefully or ask your agent to explain it in detail.
Hurricane deductibles are almost always a percentage of your dwelling coverage limit rather than a flat dollar amount. Percentages typically range from 1% to 5%, though some coastal policies carry higher amounts depending on the carrier and location. To determine your exposure, multiply your dwelling coverage by your hurricane deductible percentage. For example, if your home is insured for $500,000 and your hurricane deductible is 3%, you are responsible for the first $15,000 of hurricane-related out-of-pocket damage before your coverage pays.
Some policies carry both a windstorm deductible and a hurricane deductible. In these cases, the hurricane deductible typically applies when the storm meets the hurricane trigger, and the windstorm deductible covers all other wind events. In most cases, only one deductible applies to a single storm event, not both.
This is why you want to know your policy’s trigger language in advance and to consult with your agent. Even with hurricane coverage in place, certain types of storm damage are not covered under a standard homeowner’s policy. If a storm surge causes flooding—water that enters your home from rising water levels—a separate flood insurance policy would be required for coverage. Unless you have added a specific endorsement, sewer backup also is typically not covered. As you can imagine, pre-existing conditions before the storm also will not be covered as hurricane damage. Knowing these exclusions is just as important as understanding the deductible itself.
A hurricane can cause wind, flood, and surge damage simultaneously, and each type may require a different policy to respond. Once a named storm is within a certain range, some insurers will limit new policies or endorsements in the affected area, so make sure your coverage is in order well in advance.
We recommend that you ask your agent to walk you through your declarations page each year and confirm your hurricane deductible percentage and dollar amount. You should also know which trigger language your policy uses to activate the hurricane deductible and whether you need separate flood coverage. Equally important, make sure your dwelling coverage limit reflects current rebuilding costs.
The best time to understand your hurricane deductible is long before a storm, not when one is approaching.
